Equity Release Advisers in Lincolnshire: A home can represent decades of work, decisions and memories. Later in life, some homeowners begin asking whether part of its value could serve a practical purpose today.
Equity release advisers in Lincolnshire can help homeowners examine that question carefully.
An adviser’s role is not simply to calculate how much money might be available. It is to assess whether equity release could be suitable, explain its long-term cost and compare it with realistic alternatives.
Lincolnshire also has very different property markets. A house in Lincoln may be valued differently from a detached property near Stamford, Grantham, Sleaford, Louth or the Lincolnshire Wolds.
Those differences can affect later-life lending.
Finding an Equity Release Adviser in Lincolnshire
- Equity release normally means a lifetime mortgage or home reversion plan.
- Lifetime mortgages are the more common form.
- Your age, property value, and lender criteria can affect how much is available.
- Property type, condition and location can also influence lender acceptance.
- Interest may compound if it is added to the mortgage rather than paid.
- Releasing equity will normally reduce the value remaining in your estate.
- It may affect means-tested benefits and future financial choices.
- Existing mortgages normally need to be repaid when an equity release plan completes.
- Consider alternatives before any recommendation is made.
- An equity release adviser in Lincolnshire should assess your circumstances before recommending a product.
For a wider explanation of the product, read our guide to equity release.
What Does an Equity Release Adviser in Lincolnshire Do?
An equity release adviser examines both the immediate objective and the consequences that could follow many years later.
This distinction matters.
Accessing £30,000 today may solve a practical problem. However, the eventual cost can be substantially higher if interest is allowed to compound.
An adviser should therefore consider:
- Your age and, for joint applications, the age of the youngest applicant.
- Your property’s current value.
- The amount you want to release.
- Existing mortgages or secured borrowing.
- Your income and regular expenditure.
- Your health and lifestyle where relevant.
- Whether you intend to move.
- Your future care requirements.
- Your wishes concerning inheritance.
- Possible entitlement to means-tested benefits.
- Other borrowing or financial options.
The adviser can then determine whether equity release should form part of the discussion at all.
That is an important distinction between eligibility and suitability.
How Lincolnshire Property Values Can Affect Equity Release
Equity release is secured against property, so location and valuation matter.
Lincolnshire isn’t one uniform housing market.
Office for National Statistics figures for July 2026 show provisional average house prices of around £187,000 in Lincoln, £215,000 in East Lindsey, £243,000 in North Kesteven and £260,000 in South Kesteven.
These figures are area averages, not valuations for individual homes.
See the latest ONS housing market information for current local data.
For equity release, a lender will normally rely on an acceptable property valuation rather than an online estimate or regional average.
The eventual valuation can influence:
- Whether the property meets lender requirements.
- The maximum available loan.
- The percentage of property value that can be released.
- Which lenders may consider the application.
A higher-value property does not automatically mean that borrowing more is appropriate.
The amount required should still come first.
Property Type Matters Across Lincolnshire
Lincolnshire contains city homes, market-town properties, coastal housing and extensive rural areas.
That variety can create practical underwriting questions.
A lender may examine:
- Standard or non-standard construction.
- Remaining property value after borrowing.
- Property condition.
- Acreage and outbuildings.
- Commercial use.
- Flooding or environmental concerns.
- Lease length for flats or leasehold homes.
- Proximity to commercial premises.
- Access arrangements.
- Some forms of agricultural restriction.
- Whether the property can be readily resold.
Homes around Lincoln, Grantham and Sleaford may therefore raise different questions from properties around Skegness, Mablethorpe, Louth or rural parts of the Lincolnshire Wolds.
An adviser familiar with later-life lending can check lender criteria before an application progresses too far.
How Much Equity Could You Release?
No single percentage applies to every homeowner.
With a lifetime mortgage, the maximum loan-to-value may depend on factors including:
- Your age.
- The youngest applicant’s age for a joint application.
- Property value.
- Property type.
- The lender.
- Product criteria.
- Health or lifestyle information where enhanced terms are available.
Generally, older applicants may have access to a higher maximum percentage than younger applicants.
However, the maximum available amount should not automatically become the amount borrowed.
An adviser should first establish what you need and why.
Lump Sum or Drawdown Lifetime Mortgage?
A lifetime mortgage can sometimes provide money as a single lump sum.
Some products instead provide a smaller initial release with a reserve facility for future withdrawals.
This is commonly called drawdown.
The distinction matters because interest generally begins when you actually borrow money.
If someone needs £25,000 now but expects to need another £15,000 later, releasing the full £40,000 immediately could cause interest to accrue on money that isn’t yet needed.
A drawdown arrangement may allow you to keep funds burrowed until needed, subject to the lender’s terms and future availability.
Learn more about how these products work in our guide to lifetime mortgages.
Why Compound Interest Deserves Careful Attention
One of the most important parts of equity release advice is explaining how interest works.
Some lifetime mortgages allow interest to be added to the mortgage rather than paid each month.
Interest can then be charged on:
- The original amount borrowed.
- Previous interest already added.
This is compound interest.
The balance can therefore grow significantly over a long period.
Some plans permit voluntary repayments or regular interest payments. These may reduce the effect of interest accumulation, subject to the product’s terms and limits.
An adviser should show you a personalised illustration rather than rely on a simple headline interest rate.
The FCA requires lifetime mortgage illustrations to explain significant risks, including how the mortgage could affect inheritance, future borrowing and moving home.
What Happens to an Existing Mortgage?
An existing mortgage or other borrowing secured against your property will normally need to be repaid when a lifetime mortgage completes.
You may therefore use part of the money released for that purpose.
For example, someone approaching the end of an interest-only mortgage could consider several possible routes.
These could include:
- Repaying the mortgage from savings.
- Selling and buying a less expensive property.
- A standard residential mortgage.
- A retirement interest-only mortgage.
- Another later-life mortgage.
- A lifetime mortgage.
Equity release is therefore one possible solution, not the default.
Our later-life lending guide explains some of the wider borrowing choices available to older homeowners.
Could Equity Release Affect Your Inheritance?
Yes.
A lifetime mortgage is normally repaid from the property when the final borrower dies or enters permanent long-term care.
The amount repaid reduces what remains from the property for the estate.
Some products offer inheritance-protection features. Others may allow borrowers to make repayments that limit mortgage growth.
Those features have conditions and can affect the amount initially available.
Inheritance should therefore be part of the advice conversation rather than an afterthought.
Can Equity Release Affect Benefits?
It can.
Receiving money from an equity release plan may change your savings or capital position.
That could affect entitlement to some means-tested benefits.
How the money is released and subsequently held or spent can therefore matter.
MoneyHelper advises homeowners to consider how lifetime mortgages could affect benefits and to ask advisers about the wider implications before proceeding.
Why Alternatives Must Be Considered
Sometimes the strongest advice is not to release equity.
Depending on the homeowner’s circumstances, alternatives could include:
- Using available savings.
- Downsizing.
- Taking a smaller conventional mortgage.
- A retirement interest-only mortgage.
- Reducing the amount required.
- Delaying expenditure.
- Using existing income.
- Checking eligibility for grants or support.
- Financial assistance from family.
The FCA has previously raised concerns about equity release advice where alternatives were not explored sufficiently or recommendations were poorly personalised.
A specialist adviser should therefore understand the problem before considering the product.
For mortgage professionals, Connect for Intermediaries also provides a technical equity release advice guide covering suitability, alternatives and later-life referrals.
Family Support and Education Costs in Lincolnshire
Some homeowners consider releasing money to support children or grandchildren.
That can include helping with a house deposit or other family costs.
Lincolnshire also has independent schools in areas including Lincoln and Stamford. Families considering school fees should not assume that releasing equity from a relative’s property is automatically the appropriate solution.
Where education costs are the main objective, dedicated Education Finance guidance may provide a more relevant starting point.
The Independent Schools Council currently lists independent schools across several Lincolnshire locations, including Lincoln and Stamford.
Any gift made from equity release should first be considered against the homeowner’s own future needs.
Finding Mortgage Advice in Lincolnshire
Later-life decisions can sometimes overlap with ordinary residential borrowing.
Someone may discover that a conventional mortgage, remortgage or another structure is more appropriate than equity release.
Homeowners who need wider mortgage advice can search for a Mortgage Broker in Lincolnshire through the Connect Experts directory.
Equity release itself requires appropriately qualified and authorised advice.
Questions to Ask an Equity Release Adviser in Lincolnshire
Before proceeding, consider asking:
- Why is this recommendation suitable for me?
- What alternatives have you considered?
- How much will I owe after 5, 10, 15 or 20 years?
- Can I make voluntary repayments?
- Are early repayment charges possible?
- Can I transfer the mortgage if I move?
- Could the plan restrict the type of property I move to?
- What happens if one borrower enters long-term care?
- Could my entitlement to benefits change?
- How will the plan affect my estate?
- Can I borrow more later?
- What happens if property values fall?
- What fees will I pay?
A good advice process should leave you understanding both what the mortgage can do and what it could change.
FAQs About Equity Release Advisers in Lincolnshire
Do I need an adviser for equity release?
Equity release is a regulated form of later-life finance. Specialist advice is important for assessing suitability and understanding the long-term implications.
What age can I release equity in Lincolnshire?
Minimum ages vary between providers. Many lifetime mortgage products begin from around age 55, although individual lender criteria differ.
Does living in Lincolnshire change how much I can release?
Your postcode alone does not determine the amount. Property value, property eligibility, applicant age and individual lender criteria are important factors.
Can I stay in my Lincolnshire home after taking equity release?
With a lifetime mortgage, you retain ownership of your home. The mortgage is normally repaid when the final borrower dies or enters permanent long-term care, subject to the product terms.
Can I move after taking a lifetime mortgage?
Some lifetime mortgages can be transferred to another suitable property. The new property must normally meet the lender’s criteria, and the move may require you to repay part of the mortgage.
Does equity release reduce inheritance?
Usually, yes. The loan and accumulated interest are normally repaid from the property, reducing the amount remaining in the estate.
Can I repay a lifetime mortgage early?
Potentially. However, early repayment charges may apply. Their calculation varies between products, so this should be explained before proceeding.
Speak to an Equity Release Adviser in Lincolnshire
Property can provide security throughout life, but using part of its value changes the role that property plays in your future.
That deserves careful advice.
If you are considering equity release in Lincolnshire, an adviser can review your property, objectives, existing borrowing and future plans before discussing available products.
Speak to an adviser about your later-life options.
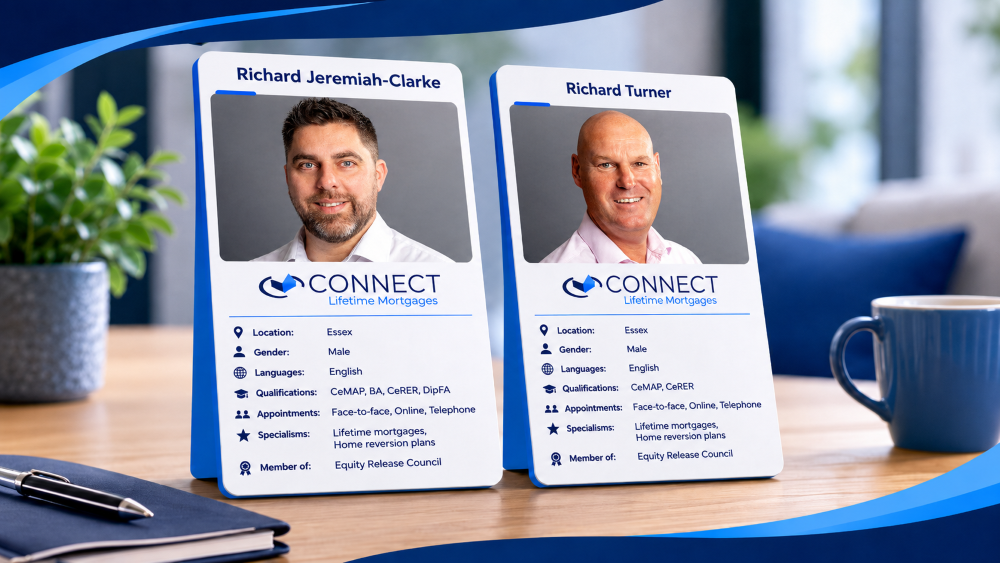
Important Regulatory Information
Equity release may involve a lifetime mortgage or a home reversion plan.
A lifetime mortgage is secured against your home. Interest may be added to the amount borrowed, which means the amount owed can increase significantly over time.
Equity release can reduce your estate’s value and may affect your entitlement to means-tested benefits.
Check that any lifetime mortgage will meet your needs if you want your family or others to inherit your home. Where appropriate, seek independent legal and financial advice.
Your adviser should explain the features, costs and risks and provide a personalised illustration before you decide whether to proceed.
Connect Lifetime Mortgages is a trading style of Richer Mortgage and Retirement Ltd, an appointed representative of Connect IFA Ltd. Connect IFA Ltd is authorised and regulated by the Financial Conduct Authority, FCA registration number 441505.
Connect Lifetime Mortgages is a credit broker and not a lender.